
Whether insurance covers kitchen water damage, and how much of the remodel it pays for, depends on your policy and on what caused the water. Many homeowners policies cover sudden, accidental leaks differently from slow leaks or outside flooding. Even when a claim is approved, it typically pays to restore what was damaged, not to upgrade it.
What Does Homeowners Insurance Usually Cover After a Kitchen Leak?
The short answer: it depends on the cause and your policy language. Many policies distinguish between water that arrives suddenly, such as a burst supply line or a dishwasher hose that splits, and water that leaked slowly over weeks or months. Gradual leaks, wear and tear, and poor maintenance are often limited or excluded.
Floodwater from outside is a separate category. FEMA's National Flood Insurance Program notes that standard homeowners policies generally do not cover flood damage. Mold coverage also varies and may be limited. The Texas Department of Insurance publishes consumer guides that explain common policy types and terms. Read your policy, call your insurer, and get answers in writing before you plan the rebuild.
Planning a Water Damage Remodeling Project?
Six Design Group designs and builds kitchens, baths and floors from Lake Highlands. Call to talk through your home and get a written scope.
- 34 Google reviews
- Design and build under one team
- Based in Lake Highlands, Dallas
- Mon–Fri 9 am–5 pm
Common Terms You Will See on a Claim
Insurance paperwork has its own language. These terms come up on most kitchen water claims:
| Term | What it generally means |
|---|---|
| Deductible | The amount you pay before coverage applies |
| Sudden and accidental | A one-time event, often treated differently from gradual leaks |
| Replacement cost | Pays to replace damaged items with similar new ones, depending on policy |
| Actual cash value | Replacement cost minus depreciation, depending on policy |
| Supplement | An addition to the estimate when more damage is found |
| Like kind and quality | Replacement with materials comparable to what was there |
Your policy defines how each one applies to you. If a term is unclear, ask your agent or adjuster to explain it in writing.
How Matching Rules Affect Cabinets and Countertops
Matching is one of the most debated parts of a kitchen claim. If two damaged base cabinets cannot be matched to the rest, does the policy pay to replace the whole run? Matching rules vary, and the answer depends on your policy and your insurer's practices. There is no single rule that applies to every claim.
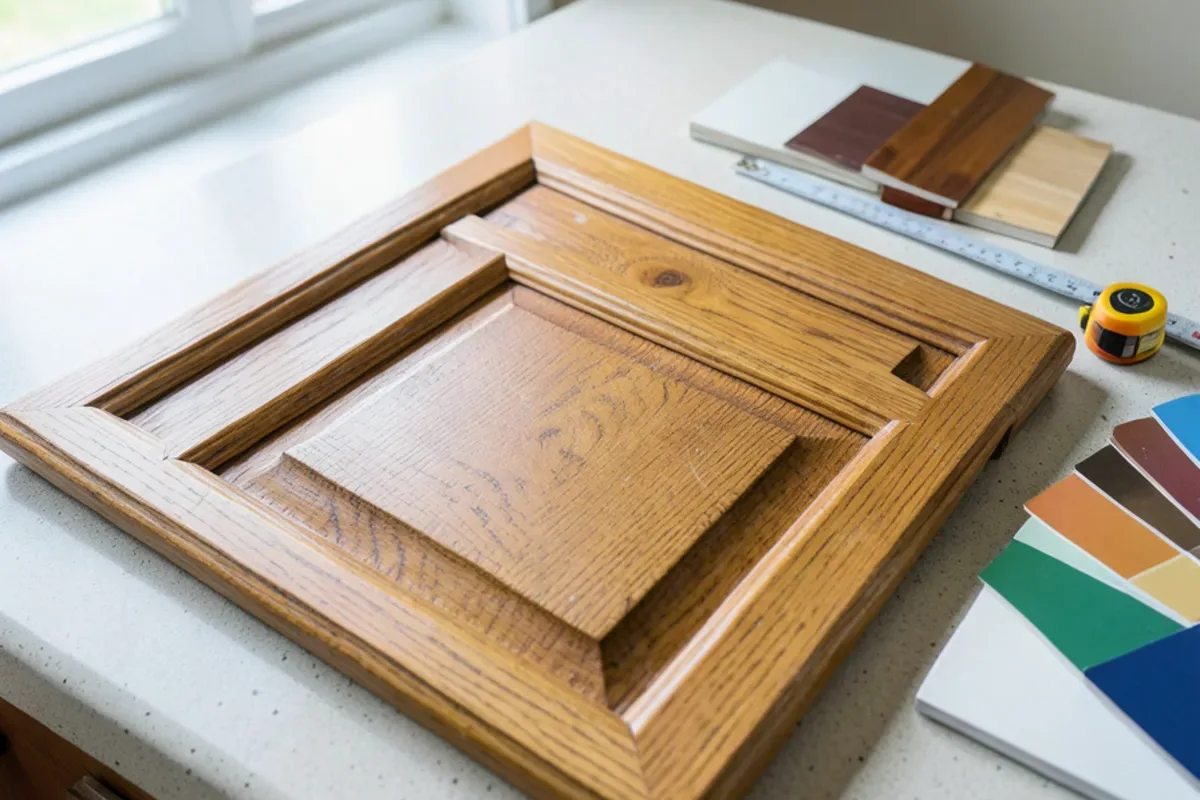
What helps is evidence. Save a cabinet door, a piece of flooring and any spare tile. Photograph finishes up close. If a cabinet line or countertop color has been discontinued, ask the supplier for written confirmation. That documentation gives your adjuster something concrete to review.
What You May Pay Out of Pocket
Even with an approved claim, some costs often land on the homeowner. Plan for these:
- Your deductible.
- Upgrades beyond like kind and quality, such as moving from laminate to quartz or changing the layout.
- Items your policy limits or excludes, which may include gradual leak damage or mold beyond a set amount.
- Work outside the damaged area you choose to include, such as remodeling the rest of the kitchen while it is open.
Many homeowners use the claim as the base and fund a broader remodel on top. That works well when covered repairs and upgrades are priced separately in writing.
Why No Contractor Should Offer to Cover Your Deductible
The Texas Department of Insurance states that it is illegal in Texas for a contractor to waive your deductible or help you avoid paying it, including by inflating an estimate so the insurer's payment absorbs it. TDI also notes that the Insurance Code requires the policyholder to pay the deductible, that insurers can ask for proof of payment, and that contracts of $1,000 or more tied to an insurance settlement must include a notice about it. An offer to "eat the deductible" is a reason to walk away, not a discount.
From Claim to Rebuilt Kitchen, Step by Step
A kitchen water claim usually moves through the same stages. Knowing them helps you see what is waiting on whom:
- Report the claim and get a claim number, then keep every note, email and name in one folder.
- Repair and dry. The plumber fixes the source and the mitigation company dries the structure and issues a drying report.
- Adjuster inspection. The adjuster sees the damage and writes the insurer's estimate of covered repairs.
- Rebuild scope. A contractor measures the kitchen and prices the rebuild line by line, so it can be compared with the adjuster's estimate.
- Reconcile and supplement. Missed items are documented with photos and sent to the adjuster as a supplement request.
- Selections and upgrades. Covered materials are chosen first, and any upgrades are priced as a separate line you pay for.
- Funds and schedule. Payment terms are confirmed, including any mortgage lender's process for releasing funds, and the rebuild is scheduled.
- Rebuild and document. Hidden damage found during construction is photographed and reported before it is covered up.
TDI's consumer guidance notes that once an insurer agrees to pay a claim, it generally has five business days to send payment. Ask your adjuster which stage your claim is in whenever the schedule stalls.
Working With Your Adjuster in Dallas and Richardson
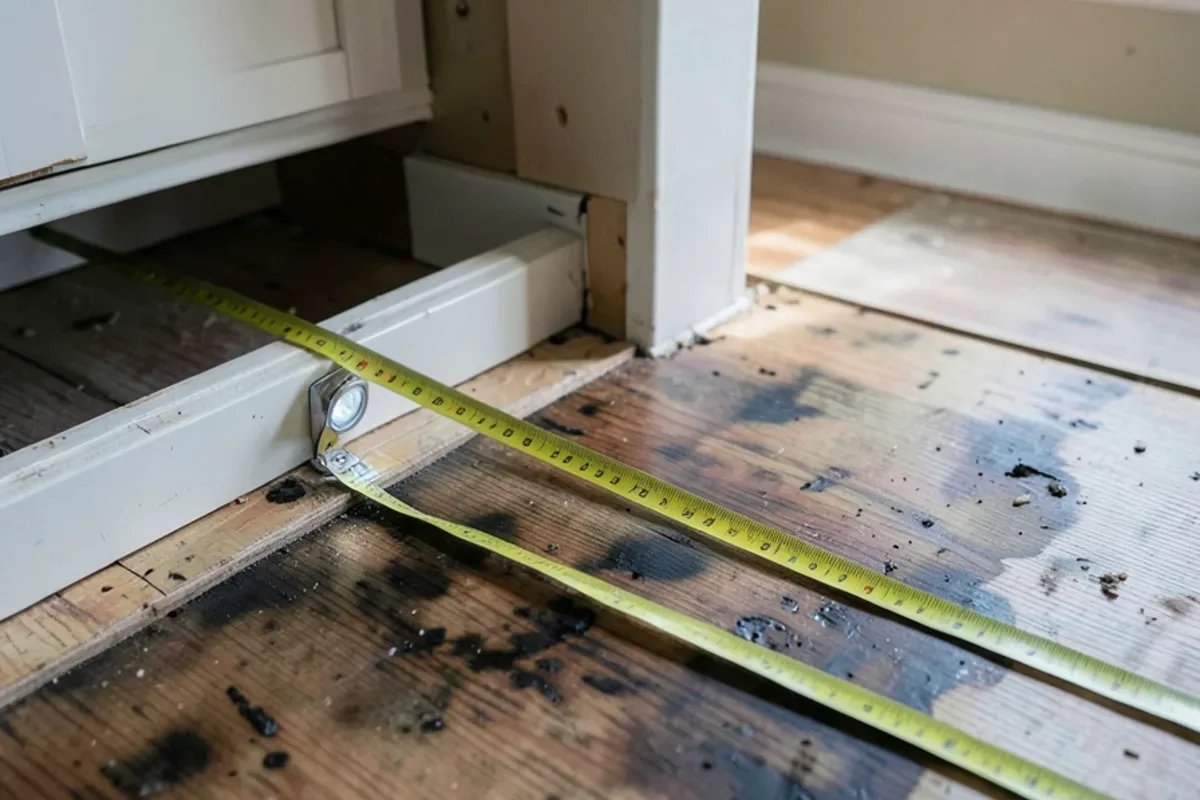
Your adjuster's estimate is a starting point. We can measure the kitchen, compare their line items with what the rebuild requires, and give you our own scope. If something was missed, such as the subfloor under a sink base or drywall behind the dishwasher, photos and measurements support a supplement request.
Homeowners in Dallas and Richardson often have older kitchens where original cabinets and tile have no current match. In those homes, matching questions come up early, so raise them with your adjuster before demolition. Texas law also sets deadlines for insurers to respond to claims, and the Texas Department of Insurance explains those rules and how to file a complaint if needed.
What We See on Insurance Kitchen Rebuilds
Our project leads find that claims go smoother when three things happen early: the damage is documented before demolition, the covered repair and any upgrades are priced separately, and selections are finished before ordering. Hidden damage is the most common change. When it shows up, we stop, photograph it and give you what you need to bring to your adjuster.
Honest pricing matters most on these jobs. Victoria W., who had us remodel her kitchen after a flood through her insurance, wrote that we told her one countertop "was twice the cost of another that was almost identical." That kind of comparison helps you decide where your own money goes.
The trade-off we lay out plainly is speed against scope. Rebuilding exactly what the claim covers is usually the fastest path back to a working kitchen. Adding a layout change or new appliances while the room is open can make sense, but it adds design time, may need a permit, and is your cost, not the insurer's. We price both so you can choose with the numbers side by side.
If mold is found, it has to be addressed before rebuilding, and in Texas mold assessment and remediation are licensed by the Texas Department of Licensing and Regulation.
Next Steps
Confirm coverage with your insurer, document everything, and get the home dried before rebuilding. Our insurance claim remodeling process keeps covered work and upgrades separate, and our kitchen water damage repair team handles the rebuild once the space is dry. Request an estimate and bring your adjuster's paperwork.
Quick Answers on Insurance Kitchen Water Damage
Can I pay the difference to get better cabinets than the claim covers?
What happens if more damage shows up once the kitchen is opened?
What should I send my adjuster before the kitchen rebuild starts?
Can I pick my own contractor for an insurance kitchen rebuild?
Sources
- Texas Department of Insurance
- FEMA National Flood Insurance Program (FloodSmart)
- Texas Department of Licensing and Regulation, Mold Assessors and Remediators
- Texas Department of Insurance, Can a Contractor Waive My Deductible?
- Texas Department of Insurance, Get Your Insurance Claim Paid
- Texas Department of Insurance, Steps to Getting Your Insurance Claim Paid
Written by the Six Design Group team
Design-build remodelers based in Lake Highlands, Dallas. We plan and build kitchens, bathrooms, floors and whole-home remodels across Dallas-Fort Worth.